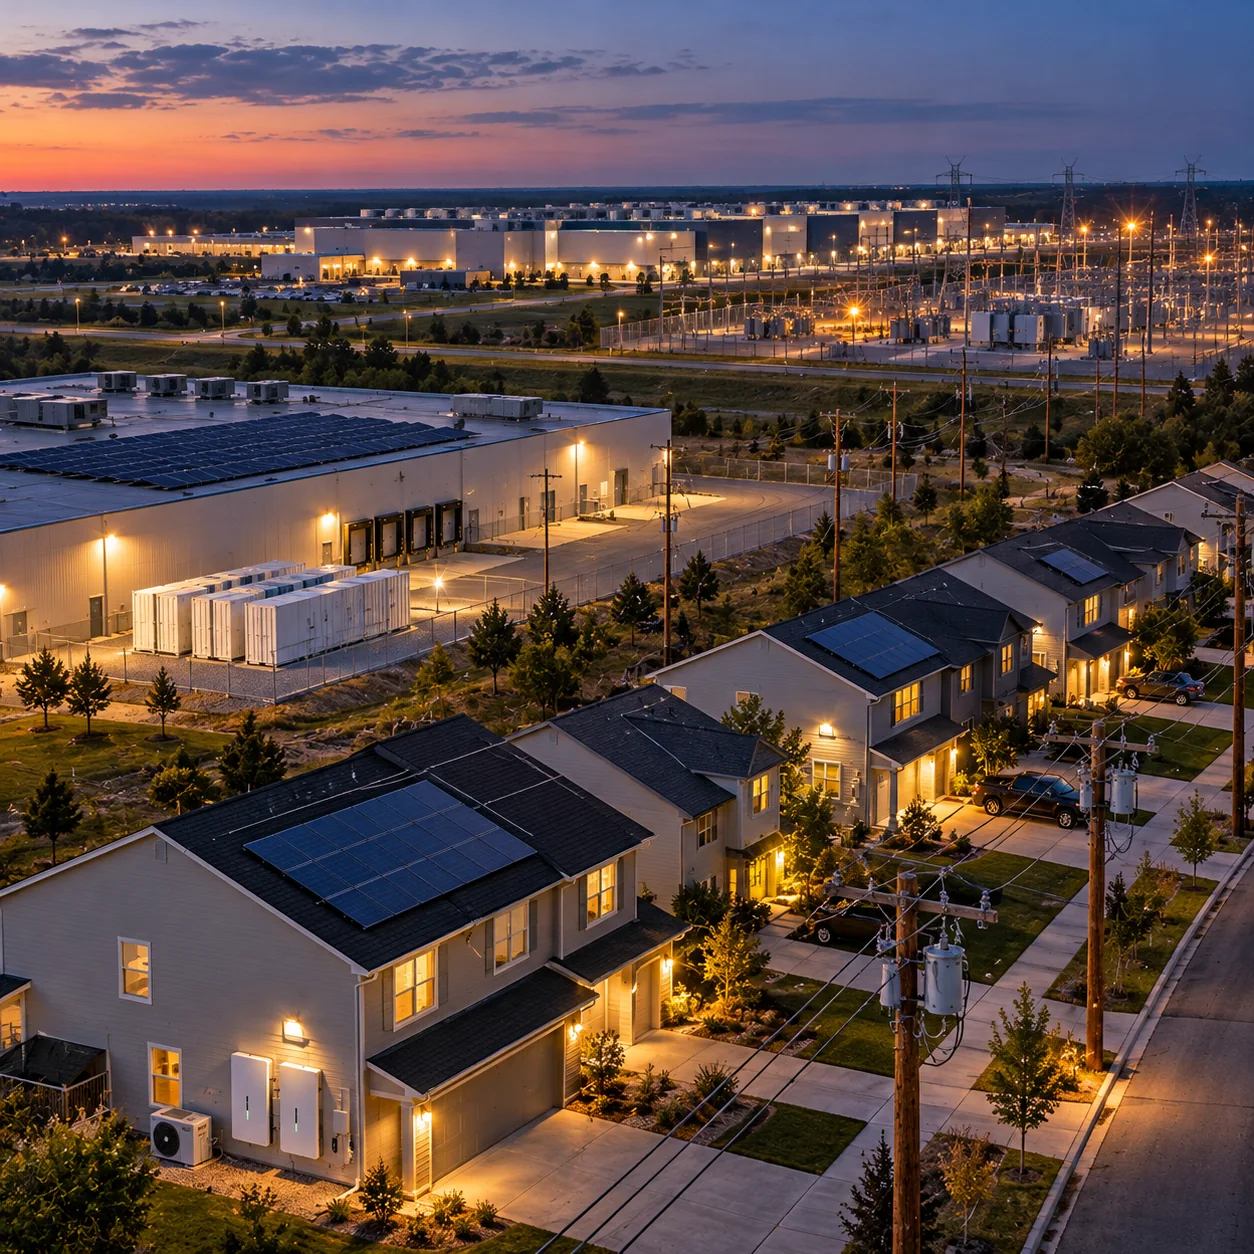
One hundred megawatts was the proof of concept. One gigawatt is a market signal.
On October 22, 2026, Google said it is adding 1,070 MW to the virtual power plant it contracted with Voltus in PJM in June, according to Utility Dive. The original agreement covered 100 MW. Combined, the program now stands at roughly 1,170 MW, close to twelve times its starting size.
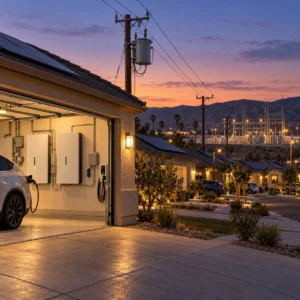
Google pays Voltus to aggregate flexible resources from residential, commercial and industrial customers, including batteries, smart thermostats, on site generation and industrial process adjustments. Voltus then offers that combined capacity into PJM’s market when the grid is under strain. A Voltus spokesperson told Utility Dive the company expects to ramp to full capacity over three to four years and run the program under its Google contract through 2040.
For the largest wholesale market in the country, which serves 13 states and the District of Columbia, the timing is hard to miss.
PJM Needs Capacity Faster Than It Can Build It
PJM has recently fallen short of its reliability margins despite sharply higher capacity auction prices, largely because of data center demand, Utility Dive reports. The grid operator set a record peak load of 168.2 GW on July 2, and interconnection queues across regional grid operators stretch for years.
That is the core problem a VPP of this size addresses.
New generation and transmission take the better part of a decade to plan, permit and connect. Distributed resources already sit behind customer meters. Aggregating them does not require a new substation or a spot in the queue, and the capacity can be enrolled in stages as contracts are signed.
Market revenue is following. According to the PJM market monitor, Monitoring Analytics, demand response revenue in PJM rose 240% from 2024 to 2025, driven mainly by higher capacity prices, with emergency demand response accounting for 88% of the total.
Large Loads Are Starting to Bring Their Own Capacity
The structure of the deal matters as much as its size. Under the contract, Voltus takes responsibility for Google’s capacity obligation. In plain terms, a data center owner is paying to create grid flexibility that offsets the load it adds.
Voltus calls the model Bring Your Own Capacity. Its chief executive, Dana Guernsey, has compared these contracts to the power purchase agreements that financed utility scale wind and solar, a comparison Utility Dive highlighted in its October 19 analysis of the program.
“Distributed energy resources are powerful tools for managing a modern, reliable grid while keeping energy affordable,” said Ellen Zuckerman, head of energy market development for North and South America at Google. She described the expansion as tenfold growth on the company’s initial commitment.
The question now is not whether hyperscalers will pay for flexibility.
It is how quickly the rest of the market follows.
Why the Economics Now Work for Customers
Participants in the Voltus program can earn up to $350,000 per MW year through demand response payments, according to the company. That level of compensation changes the conversation with commercial and industrial customers, who have historically treated demand response as a modest side income.
The wider benefits extend to households. A Brattle Group report prepared for aggregator Everyday Electric and published on October 13, 2026, found that if all US utilities cut system peak by 4% using residential VPPs, average household bill increases over the next five years could be more than halved. Brattle estimates $4 billion to $7 billion a year in financial benefits for US households, with residential VPP capacity rising from about 10 GW to 35 GW nationally.
Brattle also notes that the top 10% of utility demand response programs already reach that 4% level. The target is not theoretical.
What Utilities and Grid Operators Should Watch
A gigawatt of contracted flexibility in one market raises practical questions for the organisations that plan and run the grid:
- How aggregated resources are verified and counted toward resource adequacy
- Whether distribution planners can see where enrolled assets sit on each feeder
- How dispatch of behind the meter assets interacts with local distribution constraints
- What telemetry and settlement standards aggregators must meet at this scale
- How capacity contracts with large loads are recognised in interconnection decisions
- Where utility run programs and third party aggregators can work together rather than compete
Voltus says it has about 8.5 GW of distributed assets under contract across North America and is targeting 20 GW by the end of the decade, partly through the Bring Your Own Capacity approach. The company recently raised $225 million in a funding round.
The Next Phase Is Integration, Not Proof
Regulatory design is still catching up. Federal regulators largely rejected a PJM proposal for a bring your own new capacity framework for large loads in October, so commercial deals such as this one are moving ahead of formal market rules.
That is not unusual. Corporate power purchase agreements also ran ahead of policy before they became a standard financing tool for renewable projects. The same pattern could hold here: private contracts demonstrate the value, and market rules then formalise how distributed capacity is counted and paid.
For utilities, the opportunity is to treat aggregated customer resources as planned grid assets rather than occasional emergency tools. For grid operators, it is a source of capacity that can be added in months instead of years. For large loads, it offers a credible way to grow without leaving other customers to carry the cost.
The grid has always relied on large plants to meet peak demand. Increasingly, it can rely on millions of small ones as well.